
Loading page
Loading card
AU Small Finance Bank
Lifetime free, and you switch individual benefits on for 90 days at a time
One-time
Zero renewal fee
Uncapped rewards
Score 700+
Applying takes you to AU Small Finance Bank. CredSpy does not process applications, and the ranking on this site is never influenced by commission.
Best for
Terms structured from published copy
1 reward rate with their caps, taken from AU Small Finance Bank’s own published wording rather than checked against its terms document. Verify before you rely on a figure.
Terms effective from 10 Oct 2026.
See where each figure came fromEverything else
No published ceiling on this tier
The issuer publishes no earning exclusions for this card All exclusions
Data-driven verdict based on net earnings after fees and caps.
Key strength
5% on Everything else — Available as a selectable 90-day feature on a chosen category, with its own fee for that term. The card earns nothing until a feature is activated., with no stated cap.
Biggest limitation
A feature left switched on keeps charging its fee every 90 days, and per-feature fees are easier to lose track of than a single annual charge.
Priced with caps, exclusions, and annual fee deducted live.
Monthly spending — ₹54,000
Pricing…
Pricing…
Pricing…
Pricing…
Pricing…
Pricing…
Pricing…
Pricing…
Import a statement and this runs on your real spending instead of the sliders.
Click any drawer below to inspect fee schedules, lounge terms, reward multipliers, and exclusions.
Everything else the issuer publishes about this card. All of it is on this page and searchable — open only what you need.
5%
uncappedEverything else
Available as a selectable 90-day feature on a chosen category, with its own fee for that term. The card earns nothing until a feature is activated.
| Charge | Amount | Condition |
|---|---|---|
| Joining fee | Nil | — |
| Annual / renewal fee | Lifetime free | The card carries no annual fee, so there is no waiver to earn. |
| Add-on card | The issuer publishes no separate add-on card fee for this card. | — |
| Cash withdrawal | 2.5%, min ₹500 | 2.5% of the amount withdrawn, subject to a minimum of Rs. 500 |
| Late payment | 15% + GST | 15% of the total amount due, subject to a minimum of Rs. 10 and a maximum of Rs. 1,300, plus GST |
| Foreign currency markup | 3.49% | — |
Interest only applies if a balance is carried past the due date. Paying in full each month costs nothing, and no reward rate on this card comes close to offsetting the interest if you do not.
Fees exclude GST unless stated. Charges can change — confirm against the issuer's current schedule before applying.
Year one
Rewards only
no welcome value is recorded
Every year after
No fee, ever
the rewards simply continue
The issuer publishes no additional spend condition for this card's lounge access.
No fuel surcharge waiver is published for this card.
Only RuPay credit cards can be linked to UPI, so this card cannot be used to pay by UPI.
We do not have welcome or milestone benefits recorded for this card. Check the issuer's page before relying on it.
Scored against these published criteria only. No bureau pull, and no approval guarantee — the issuer decides.
CredSpy never collects these. You submit them to the issuer during their own application.
No reviews yet
CredSpy publishes only reviews left by real cardholders. Nothing here is generated, bought or seeded — so this stays empty until someone who holds the card writes one.
 AU Small Finance BankAU Bank Xcite Ultra Credit Card₹884
 AU Small Finance BankAU Bank Altura Plus Credit Card₹499
 AU Small Finance BankAU Bank Altura Credit Card₹199
 AU Small Finance Bankixigo AU Credit CardLifetime freeSuryoday SFB FD-Backed Credit CardSuryoday Small Finance BankSuryoday SFB FD-Backed Credit Card₹177
| Card | Annual fee | Headline rate | Lounge |
|---|---|---|---|
| AU Bank LIT Credit Card · this card | Lifetime free | 5% everything else | No |
| AU Bank NOMO Credit Card | ₹0 | Up to 2 reward points per ₹100 | Included |
| AU Bank Xcite Ultra Credit Card | ₹884 | Up to 12 reward points per ₹100 | Included |
| AU Bank Altura Plus Credit Card | ₹499 | Up to 1.5% cashback | No |
| AU Bank Altura Credit Card | ₹199 | Up to 2% cashback | No |
Headline rates are not comparable on their own — each card caps and excludes differently. Run your own spending through the switch calculator to see which of these actually pays you more.
It is a lifetime-free card — there is no annual fee.
The strongest published rate is 5% on everything else, with no stated cap. The calculator above prices your own basket with every cap and exclusion applied.
No — airport lounge access is not offered on this card.
Only RuPay credit cards can be linked to UPI, so this card cannot be used to pay by UPI.
The issuer publishes no earning exclusions for this card The issuer publishes no earning exclusions for this card. The issuer publishes no excluded spend categories for this card.
Redeemed through the issuer's rewards programme as published on the card's product page
You can apply online through our website by filling out the application form and uploading the required documents. You may also visit your nearest branch for in-person assistance.
Yes, you can request a limit increase through internet banking, mobile app, or by contacting customer care. Approval depends on your credit history and income. If you want, I can also create a more engaging, SEO-friendly FAQ section for your credit card website that boosts trust and conversions. Would you like me to prepare that next?
A late payment fee and interest will be charged. Missing payments can also impact your credit score.
The card is lifetime free, and its benefits are bought individually. You switch a feature on — 5% cashback on a chosen category, airport lounge access, an OTT subscription — and it runs for 90 days from activation, with its fee levied for that term. Switch nothing on and the card costs nothing and does very little.
The card is: AU charges no joining fee and no annual fee. The features are not. Each one you activate carries its own fee for its 90-day term, so your actual cost depends entirely on what you switch on — which is the point of the card and also the thing to watch.
A feature left switched on keeps charging every 90 days whether you use it or not, and because the fees are per feature rather than one annual line, they are easier to lose track of than a single renewal charge. The card rewards somebody who reviews it quarterly and quietly costs money for somebody who does not.
Somebody whose needs change through the year. Lounge access switched on for the quarter you travel in, cashback switched on for the quarter you are furnishing a house, nothing switched on for the two quarters in between — and no annual fee bought a bundle you only half wanted. If your spending is steady and predictable, a fixed-fee card is simpler and probably cheaper.
Yes, two of them. The lounge feature has to be switched on and paid for, and AU's bank-wide rule still applies on top: complimentary domestic airport lounge access needs at least Rs. 20,000 of spending in a calendar quarter, in that same quarter, and only for the primary cardholder.
AU publishes a 3.49% foreign currency markup on this variant, at the market standard. AU's own ixigo AU card is lifetime free and charges 0.99%, so for foreign spending that is the card to hold from this issuer — and since both are free, there is no reason not to hold both.
Every other card in this catalogue works the same way: one annual fee buys a fixed bundle of benefits, and you pay it whether you use all of them or one. LIT inverts that. The card is lifetime free, and the benefits are bought individually — 5% cashback on a chosen category, airport lounge access, OTT subscriptions — with each feature running for 90 days from activation and carrying its own fee for that term.
So the card costs nothing when idle and exactly what you chose when it is not. That is a genuinely different proposition, and it is the only one of its kind here.
Somebody whose needs move through the year. Switch lounge access on for the quarter you fly in, switch cashback on for the quarter you are furnishing a flat, switch nothing on for the quarters in between — and no annual fee has bought you a bundle you half wanted.
If your spending is steady and your needs do not change, the model works against you. A fixed-fee card is simpler to compare, easier to budget for, and usually cheaper than several features kept switched on all year.
Features renew. A benefit left switched on keeps charging its fee every 90 days whether it gets used or not, and because the charges arrive per feature rather than as one annual line, they are easier to miss on a statement than a single renewal.
AU also does not publish one consolidated table of every feature's fee in one place, so working out what a chosen combination costs over a year means adding it up yourself. The card rewards a quarterly review and quietly costs money without one.
Credit card fees, rewards and benefits change. Please verify the latest terms on the issuer's website before applying. CredSpy earns a commission on some applications; it never affects rankings or what is written here.
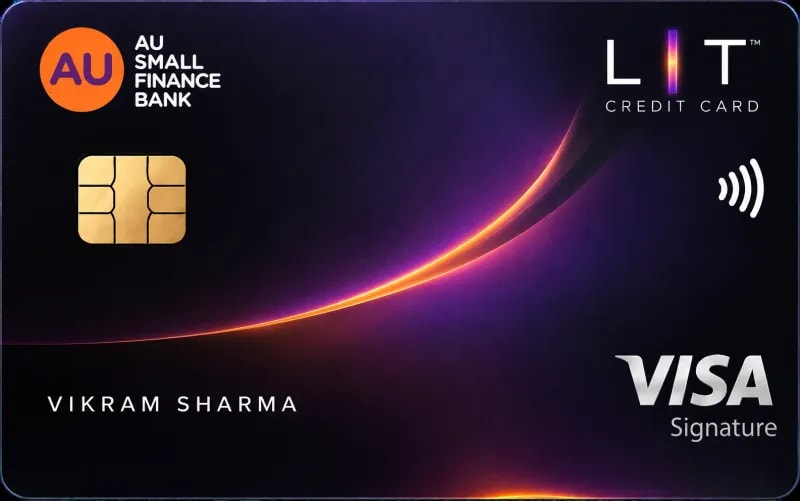
AU Bank LIT Credit Card — 5% on everything else. No annual fee.